


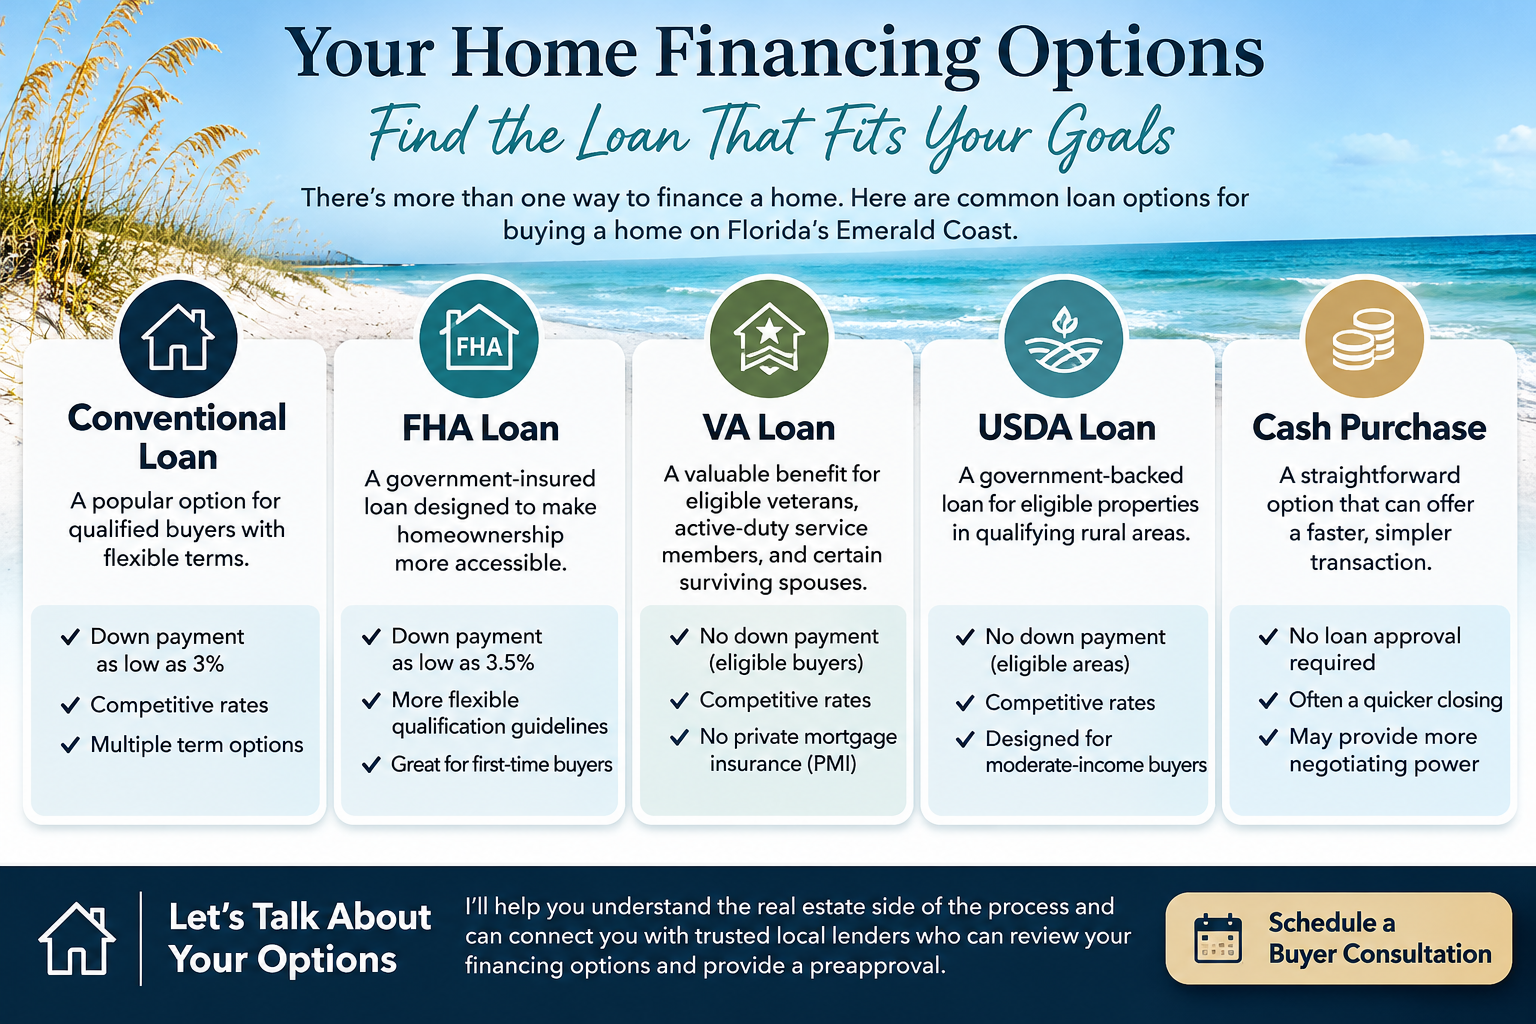
Understanding Your Financing Options
Knowing Your Budget Is the First Step Toward Buying With Confidence.
Before beginning your home search, I recommend speaking with a qualified mortgage lender to review your financing options and obtain a preapproval.
A preapproval helps establish a realistic budget and can strengthen your offer when you find the right home.
Depending on your qualifications and financial goals, financing options may include:
Conventional Loans
A popular option for qualified buyers, with different down payment requirements and loan programs available. Some conventional loans allow down payments as low as 3%.
FHA Loans
Government-insured loans that may offer more flexible qualification requirements. Eligible buyers may qualify with a down payment as low as 3.5%.
VA Loans
Available to eligible veterans, active-duty service members, and certain surviving spouses. VA loans may offer financing with no down payment, subject to eligibility and lender requirements.
USDA Loans
Designed for eligible properties in qualifying rural areas and buyers who meet income and other program requirements. Some USDA programs offer no-down-payment financing.
Cash Purchases
Buying with cash can simplify certain financing requirements, but inspections, title review, insurance considerations, and property evaluations are still important.
I'll help you understand the real estate side of the process and can connect you with lending professionals who can explain your financing options in greater detail.
Remember: Your purchase price is only part of the equation. Property taxes, homeowners insurance, flood insurance when applicable, HOA dues, and CDD assessments can all affect your monthly housing costs.